Support CleanTechnica’s work through a Substack subscription, on Patreon, or on Stripe. Help us produce all of the high-quality, original content we publish week after week despite the challenges of content-scraping AI, antisocial media, inflation, and other hurdles.
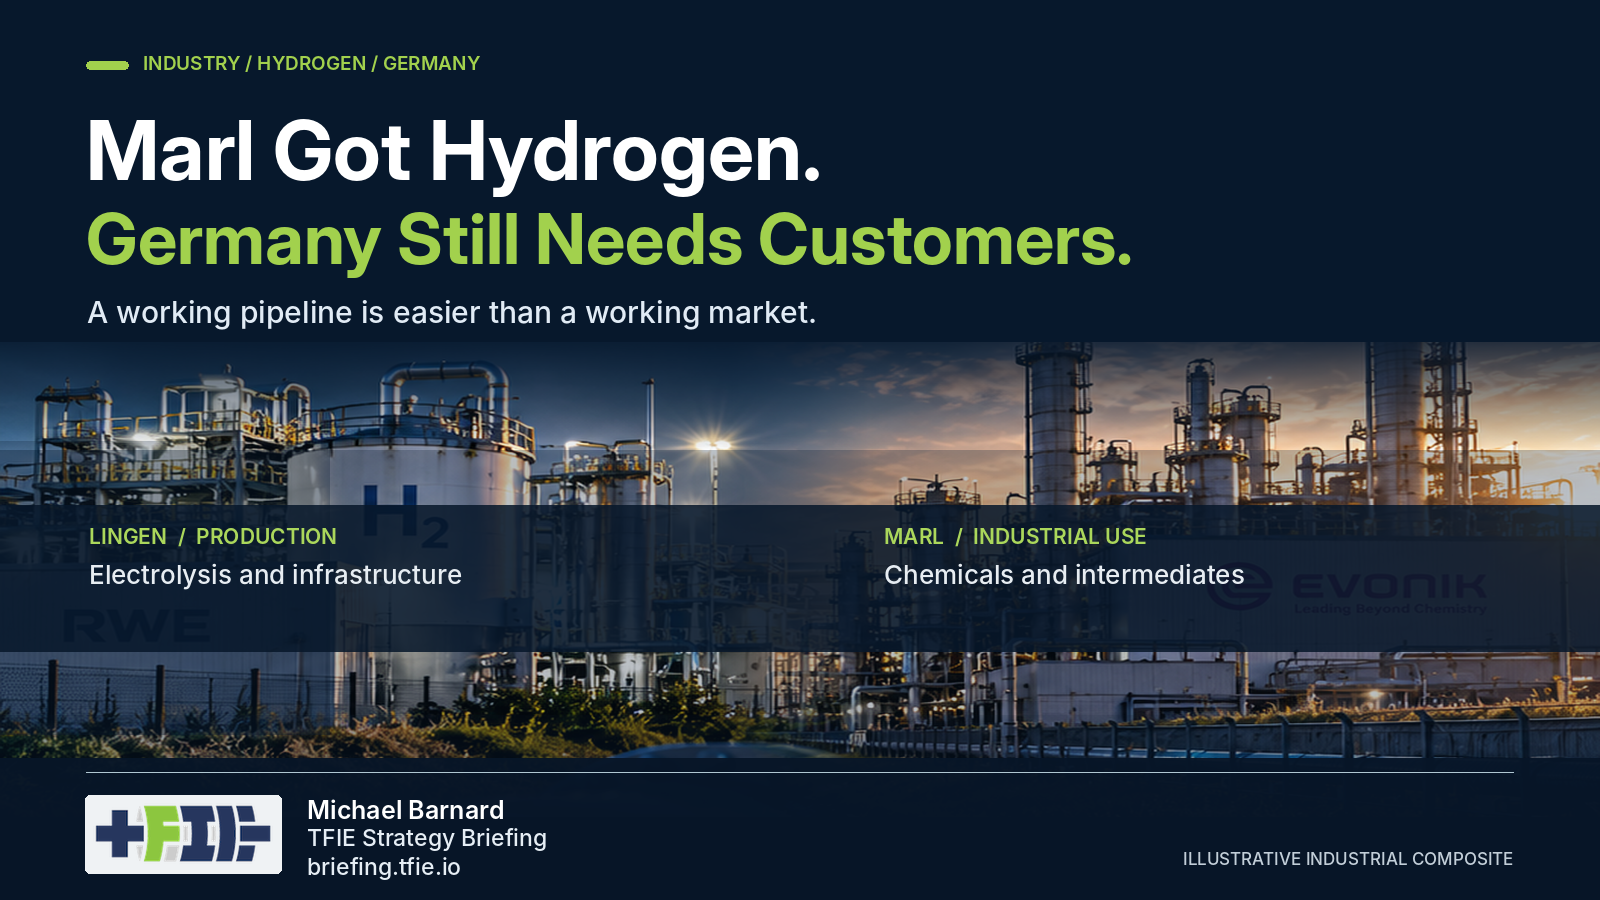
Germany’s hydrogen backbone achieved a genuine milestone on August 4, 2026. RWE and its partners announced that renewable hydrogen produced during commissioning at Lingen had reached Marl Chemical Park, roughly 120 kilometres away. Electrolysers, converted natural gas pipelines and industrial receiving infrastructure were working together.
The GET H2 consortium deserves credit for getting the equipment operating. But completing a hydrogen pipeline and establishing an economically competitive market for the hydrogen moving through it are different achievements.
The announcement did not disclose the quantity received at Marl, the price paid by an industrial customer or which existing hydrogen production was displaced. The English release describes hydrogen being available for industrial use, while the German release says it was used. Neither provides the industrial mass balance needed to determine the actual emissions benefit. The network also contained hydrogen from earlier commissioning activities, which makes tracing individual molecules through the pipeline less useful than measuring what changed at the receiving industrial facilities.
Marl is hardly a new hydrogen customer. The chemical park has used hydrogen for decades in integrated production processes. Providing another source may be useful, especially where renewable hydrogen replaces fossil-derived supply, but existing demand does not automatically become commercially viable demand for a considerably more expensive feedstock.
The larger infrastructure ambition makes that distinction important. Germany’s approved hydrogen core network covers 9,040 kilometres and has expected investment costs of €18.9 billion. Much of the network will use converted natural gas pipelines. These are approved plans and anticipated investments, not evidence that the entire network has been built or that future customers have committed to using it.
There are genuine industrial commitments. RWE has a 15-year agreement with TotalEnergies to supply approximately 30,000 tonnes of renewable hydrogen annually to the Leuna refinery from 2030. That provides a named customer, volume and contract period. The price is undisclosed, and European fuel regulations help create demand for renewable hydrogen in refining.
That is a much stronger commercial signal than commissioning a pipeline. The question is how many comparable customers exist, what they can afford and whether their businesses will continue using hydrogen over the decades required to recover infrastructure investments.
The wider European outlook has become less optimistic. ENTSOG’s October 2026 draft assessment reduced its 2030 hydrogen demand assumption from 620 TWh to 335 TWh, a 46% reduction from its 2024 assessment. Its 2040 assumption fell 33%, from 1,929 TWh to 1,296 TWh. These are changes to European planning scenarios, not measurements of declining actual hydrogen consumption, but they matter when infrastructure economics depend on demand growth.
My central model of hydrogen supplied through the Lingen system produces an illustrative delivered cost of about €9.06/kg after assumed capital support, compared with a €3/kg conventional hydrogen benchmark. Those are scenario values, not RWE’s actual costs or the undisclosed price paid at Marl. The gap illustrates the challenge facing industrial manufacturers selling chemicals into competitive international markets.
Hydrogen remains an important industrial feedstock. Well-located connections between producers and customers with durable demand may be worthwhile. Germany needs evidence that the customers and products can support the investment, rather than assuming that building enough pipelines will bring the market into existence.
My full TFIE Strategy Briefing analysis examines the delivered hydrogen costs, industrial manufacturing alternatives, revised European forecasts and financial exposure of Germany’s planned backbone. The detailed scenario models and implications for industrial competitiveness are available to paid subscribers.
Sign up for CleanTechnica’s Weekly Substack for Zach and Scott’s in-depth analyses and high level summaries, sign up for our daily newsletter, and follow us on Google News!
Have a tip for CleanTechnica? Want to advertise? Want to suggest a guest for our CleanTech Talk podcast? Contact us here.
Sign up for our daily newsletter for 10–15 new cleantech stories a day. Or sign up for our weekly one on top stories of the week if daily is too frequent.
CleanTechnica uses affiliate links. See our policy here.
CleanTechnica’s Comment Policy