
Ontario Power Generation has acknowledged that its first GE Vernova Hitachi BWRX-300 small modular reactor at Darlington will exceed its C$7.7 billion approved budget and miss its October 2030 commercial-operation target. There is no replacement cost or completion date yet. OPG expects its engineering, cost and schedule review to be substantially complete by mid-2027.
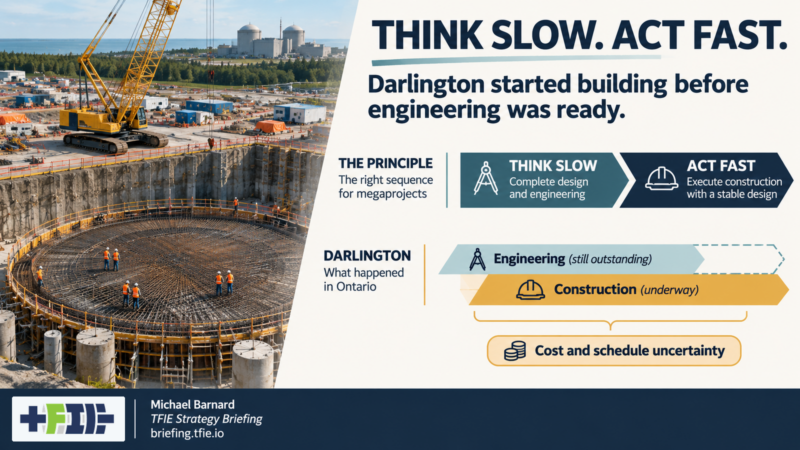
The reason matters. In its November 10 financial results, OPG identified continuing first-of-a-kind reactor engineering and its effects on construction execution and supply-chain performance. Ontario started physical work while parts of the design governing that work were still evolving. The project is now living with the consequence.
This is not a story about a construction crew failing to install a basemat. The 2.1-million-pound reactor foundation is in place, work on the turbine building has progressed, and the cooling-water tunnel equipment has been assembled. These are real achievements. They do not settle the engineering dependencies, supplier requirements and delivery sequence for a first-of-a-kind reactor. Construction progress and schedule certainty are different things.
Megaproject researcher Bent Flyvbjerg calls the better approach “think slow, act fast.” Engineering, interfaces and execution plans need enough maturity that construction can advance without a succession of disruptive changes. Design and construction can overlap on controlled, ready-to-build work packages. Darlington’s own disclosure shows that the required boundary has not been maintained.
My TFIE Strategy Briefing on Darlington’s SMR examines the November disclosure, the historical nuclear construction record and the consequences for Ontario’s four-reactor plan.
Ontario is an unusually favourable test for the Western SMR industry. OPG operates a large nuclear fleet and has an experienced workforce, an established site, transmission infrastructure and public financial backing. GE Vernova Hitachi has extensive boiling-water reactor experience. Yet the BWRX-300 is still a new design, and the promised economies of repeat construction depend on its becoming stable enough to repeat.
The four-reactor programme originally carried a C$20.9 billion budget. Within that were C$6.1 billion for the first reactor, C$1.6 billion of common infrastructure and C$13.2 billion for Units 2 through 4. The financial proposition depends on the later reactors becoming cheaper after the first teaches suppliers and builders how to execute the design.
In my October 2025 assessment I applied historical nuclear construction reference-class uplifts rather than relying only on the project’s internal estimates. A 67% uplift to the Unit 1 reactor component, with shared infrastructure held unchanged, produces a C$11.8 billion first-stage cost. A 202% uplift produces about C$20.0 billion, or nearly 96% of the original budget for all four reactors. These are illustrative stress outcomes from the historical construction class, not new OPG estimates. They show how much of the programme’s financial margin depends on getting the first design and subsequent learning right.
The uncertainty has already reached Ontario’s electricity planning. In its November 10 filing to the Ontario Energy Board, OPG withdrew the Darlington SMR generation forecast from its 2027–2031 rate application. Previously planned production of about 0.5 TWh in 2030 and 1.9 TWh in 2031 is no longer included. The filing does not announce a post-2031 commissioning date. It shows that the earlier production assumptions cannot support the regulatory request.
Ontario does not need to suspend other electricity decisions while it waits for a revised reactor budget. The Independent Electricity System Operator’s May 2026 LT2 energy procurement secured 1,115 MW of new wind and solar contracts, with expected annual generation of about 2.37 TWh and a weighted average fixed price of C$88.84/MWh. That is approximately the annual electricity a 300 MW reactor would generate at a 90% capacity factor. Ontario also contracted 640 MW of battery capacity at C$563.48 per MW-business day.
Wind and solar provide energy on a different hourly profile from a nuclear reactor. The battery procurement buys capacity services, not 640 MW of round-the-clock generation. Ontario’s decision is to assemble a reliable portfolio from the new energy, existing nuclear and hydroelectric generation, storage, interties, transmission and flexible demand. The whole-system cost of that portfolio is the relevant comparator for the next three SMRs, not a claim that a wind farm is a nuclear reactor with a different name.
This distinction also matters for the C$127/MWh comparison in my longer analysis. That figure allocates the renewable contracts’ initial energy payments and separate battery capacity payments across expected renewable production. It establishes a useful procurement spending benchmark. Additional charging, integration, transmission and dependable capacity requirements must be assessed to establish a comparable delivered system service.
Before Ontario commits to Units 2 through 4, it should require a credible outside-view update of the first unit’s cost and schedule, disclosure of outstanding design packages and their interfaces, measured evidence of construction learning, and a system-level comparison against resources that can be delivered during the same period. Each proposed later reactor is an investment decision, not an automatic entitlement created by spending on the first.
Ontario’s existing nuclear fleet is a valuable low-carbon resource. Keeping it productive and refurbishing it where justified remains important. The problem is treating a first-of-a-kind nuclear construction programme as reliably cheap future supply before engineering and costs support that conclusion.
Read the full Darlington assessment for the reference-class cost exposure, financing sensitivities and the investment gates Ontario should apply. The linked Flexibility Mesh report develops the system-services and grid-utilisation side of the comparison.